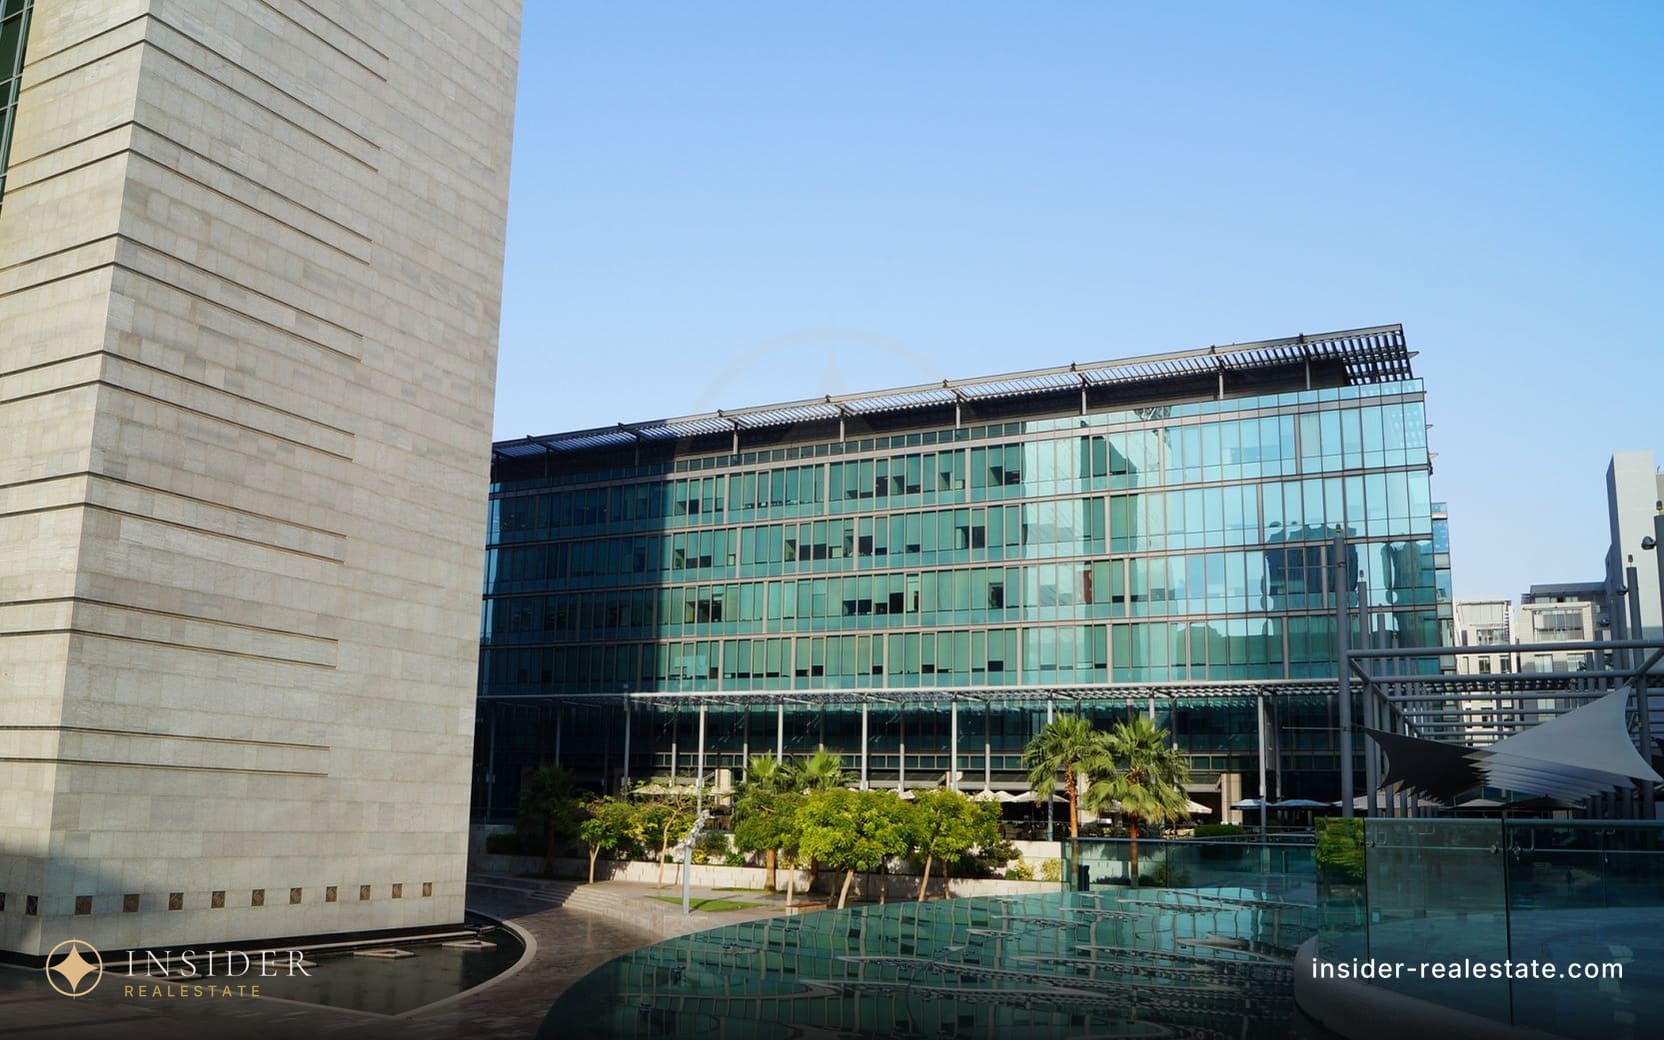
The body that runs the Dubai International Financial Centre and, at the same time, builds housing inside it — an unusual overlap of regulator and developer roles, and a residential portfolio under this name that is only two projects deep and still young.
2 projects by this developer in the catalogue. Nothing of
theirs is in the discounted stock right now — nearby listings are below.
Housing within walking distance of financial-centre jobs
Buyers who value a common-law legal framework
Steady rental demand from a narrow but well-paid tenant pool
Those who value an orderly, predictable district management structure
The company in brief
Checkable facts about the developer itself. Unlike the figures above, these are not
about our stock and do not move with what happens to be listed today.
Role
DIFC Authority runs the financial free zone; the development arm under the same name builds housing inside the very district the zone administers
First residential project
DIFC Living — over 170 units, completion by mid-2026; sold out at a record pace after launch
Second residential project
DIFC Heights Tower — 366 residences from one-bedroom apartments to four-bedroom duplexes, the final residential address in the district's master plan, completion by 2029
Not to be confused with
Central Park Towers in the same district — a separate project by other developers, not part of DIFC Authority's own portfolio
What kind of developer this is
An unusual double role: regulator and developer at once
DIFC Authority is first and foremost the body that runs a free economic zone: it licenses financial firms, maintains its own legal system and courts, and is responsible for the district's infrastructure. Residential development is a comparatively new line for it, and here the same structure acts not as regulator but as the counterparty selling apartments to private buyers.
For a buyer, that unusual overlap of roles both eases and adds concerns. It eases them because the body responsible for the zone's rules has an objective interest in the district's long-term wellbeing greater than an outside commercial developer with one project in the quarter. It adds concerns because the dispute-resolution mechanism between a buyer and a developer, when both are effectively part of the same structure, is worth confirming specifically rather than assumed.
A young but fast-growing residential portfolio
The first residential project under this name sold out noticeably faster than a new district would typically expect: demand confirmed that living next to a job in the financial centre appeals to a wider pool of buyers than just employees of local firms. The second project is larger by unit count and is positioned as the final residential address in the district's master plan — the last plot available for development in this part of DIFC.
Two projects over a relatively short span is not a long delivery history to judge a developer's behaviour through economic cycles, but it is confirmation that demand for housing in the district is real and durable. Delivery discipline is best judged by how the first project actually hands over, once it does, rather than by marketing promises for the second.
Who lives here, and why
The pool of tenants and buyers in this district is narrow but stable: people who work in the zone or nearby, often on a corporate package and a long lease. There is very little land left for new development in the district, which is a structural argument for price — supply here cannot grow as sharply as in new master plans on the city's edges.
The flip side of that same narrowness is the district's weekday rhythm: busy during working hours, quiet at weekends. That is a deliberate choice for some buyers and a reason to look at more residential districts for others, and it is worth discussing before a viewing, not after.
The legal framework this all runs on
The zone operates under its own civil and commercial law, built on common law rather than the UAE civil code that applies across the rest of Dubai. It has its own English-language courts, and a property dispute inside the zone is heard there rather than in Dubai's court system. Ownership is registered through the zone's own register rather than the standard Land Department procedure.
For a CIS buyer that is often an advantage — more familiar contract structures and proceedings in English. But legal advice built on mainland Dubai practice does not automatically transfer here, and for a specific deal it is more reliable to check with the zone's own registrar than to rely on experience from deals elsewhere in the city.
What to check before buying
Confirm the registration procedure and ownership form for the specific building in writing, not from a sales pitch, and which court and which law apply to your contract — read the dispute-resolution section rather than assume it mirrors mainland Dubai. Check the service-charge structure separately: in a dense business district, security and shared-systems costs are often higher than in a residential master plan on the edge of the city.
Separately, confirm parking — in a compact business district that is a real constraint, not a formality — and actual rents inside the zone from live listings, rather than a general impression of the surrounding area.
How I work with this developer
For a client considering an apartment here, I always start with a lifestyle question: does the business district's weekday rhythm suit them, or do they need a residential setting with weekend activity — that decides whether this address should even be compared against ordinary Dubai residential districts. Second, for the second, still-under-construction project, I track how the first one is actually handing over, since that is currently the only available benchmark for the developer's pace and quality.
Third, I always pull live achievable rents specifically inside the zone, not DIFC as a whole together with neighbouring commercial towers: the residential segment here is small, and district-wide averages can distort the real picture of a specific apartment's yield.
Lots are matched to DIFC Authority by project name, since the base has no developer field. The numbers above therefore describe our stock rather than the company’s market share: a developer with a large completed portfolio can show fewer lots than one whose buildings are resold more often.
All prices are asking prices, not sales. For the building you pick I pull the registered Land Department transactions and show the prices deals really closed at.
Video
DIFC Authority on video
Project breakdowns from the English channel. Every clip has a written version on a page of its own.
DIFC Living — 41 floors and 170 homes sold by the DIFC Authority itself — launched in September 2023 with handover scheduled for Q3 2026; our stock shows units at AED 3.85–5.4m. Next up: Four Seasons (Q1 2027), DIFC Heights (2029) and The Residences DIFC (Q4 2029).
The authority that governs and develops the Dubai International Financial Centre. Property inside DIFC sits under a different legal framework from the rest of the city — and that is the whole story.
The site catalogue covers 2 projects by DIFC Authority, each with a building passport — storeys, units, handover date and bedroom mix. They are listed above. Any lots on sale appear directly beneath their project.
Should I buy from DIFC Authority direct or through a broker?
The price is the same: on off-plan the developer pays the broker’s commission, not the buyer, so going straight to the sales office saves nothing. The difference is elsewhere — a developer’s sales office shows its own projects only, and will not tell you that the same thing next door is cheaper or that this project is running later than advertised. On resale and assignment the commission is the standard 2% plus VAT.
Is DIFC Authority worth buying
That depends on what you buy and why. Describe the budget and the aim — I will point out which of this developer’s buildings are justified today and which are better left alone.