 −3%
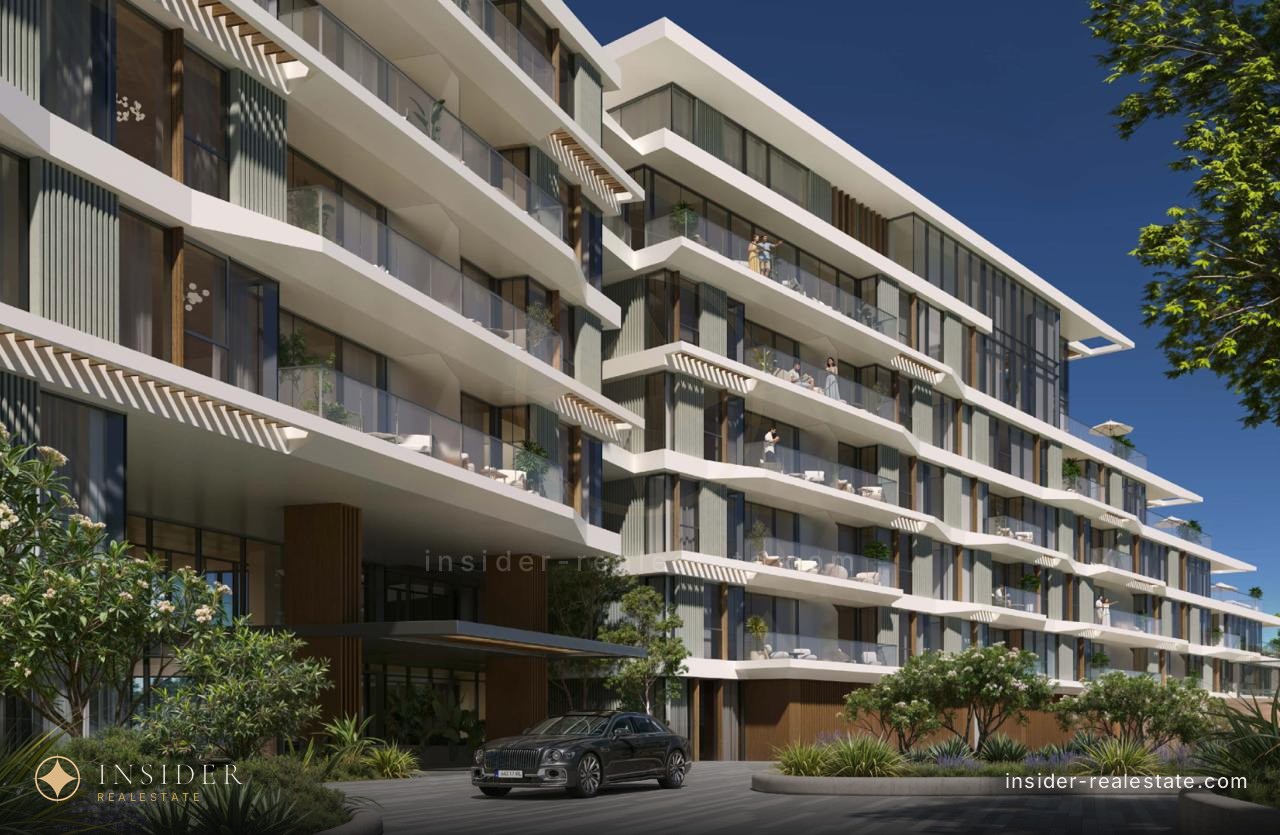
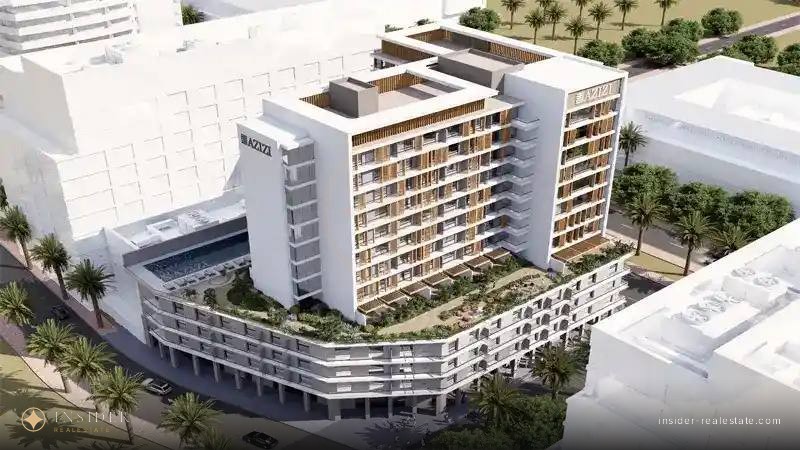
Palm Central Private Residences Frond M Building A
2 BR · Apartment
AED 4 500 000 AED 4 650 000
Nakheel’s second palm: twice the size of the first, dredged in the 2000s, abandoned for fifteen years and relaunched in 2023.
2 units in stock. 2 with a confirmed status: 0 ready, 2 under construction. 46th most expensive of 80 districts by median price.
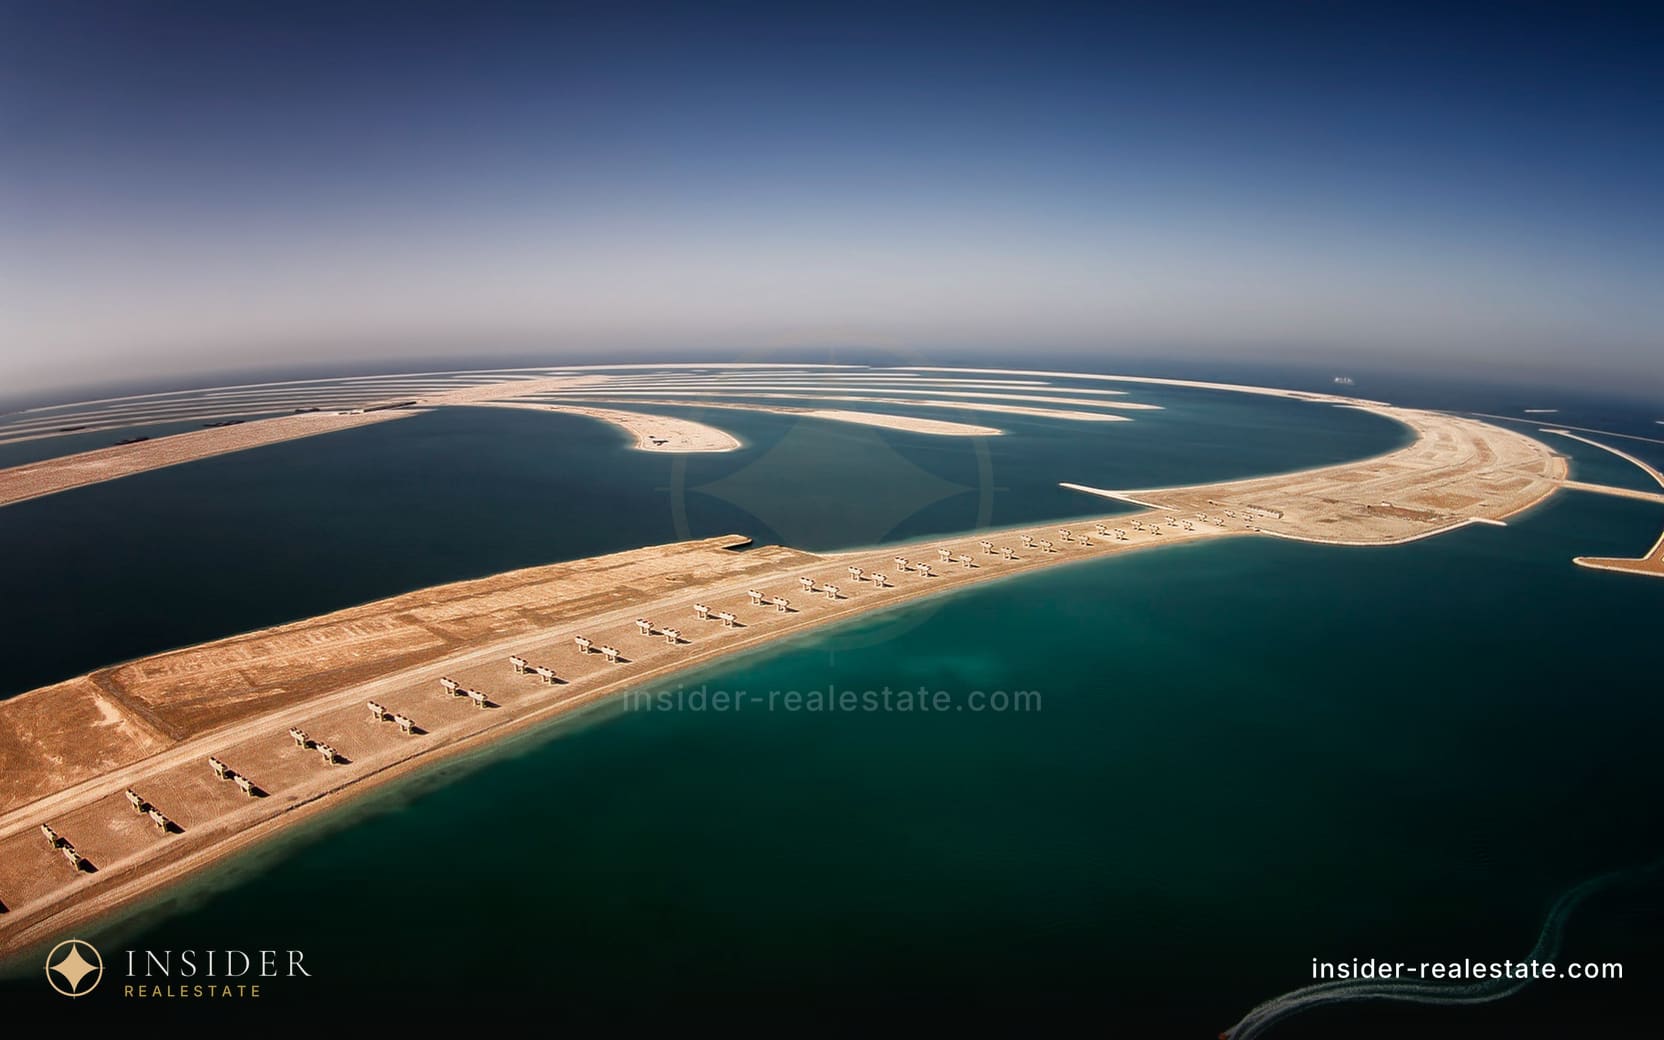
The second palm island, lying south of the first, closer to Jebel Ali. In area it is roughly twice the size of Palm Jumeirah, and the master plan gives it more than a hundred kilometres of shoreline.
The land was reclaimed in the mid-2000s. Then the crisis of 2008–2009 arrived, the project stopped, and for the following fifteen years the island stood empty — no roads, no services, not one house.
Sales resumed in 2023: Nakheel released villas on the fronds, followed by phases with apartments and plots. First handovers are expected in the second half of the decade.
A foreigner takes full freehold. Do not confuse the island with the industrial district of Jebel Ali on the mainland: different places, different rules, different prices.
This project has already been stopped once. That happens, and it is not an accusation against the developer — the 2008 crisis halted more than one scheme in Dubai. But the fact stands, and it belongs at the top of a buyer’s model rather than in a footnote.
The practical consequence is the horizon. What is bought is not a house but a master plan spanning a decade, and living beside construction will take years. Anyone who needs a finished property has no business here.
The second consequence is infrastructure. There is none on the island today: roads, services, the highway junctions and everything else are being built alongside the housing. A school and a shop on the plan are a promise, not something that can be verified.
The third is comparison. Palm Jumeirah sells on being finished: beaches, hotels, restaurants, a secondary market with transaction history. The second palm has none of that yet, and the price is lower for precisely that reason rather than because somebody has mispriced it.
The finite frond. Shoreline is limited, and there will be exactly as many waterfront villas on the island as the plan draws. On Palm Jumeirah that factor turned out to be decisive for prices.
The south of the emirate is developing: Al Maktoum airport, the port, the industry around them and the housing that follows. The island does not stand in a vacuum but beside the part of the city the centre of gravity is moving toward.
And the scale of the scheme itself: Nakheel is building a district for tens of thousands of families, and in Dubai such things generally do get finished — just later than promised.
Escrow: which account payments go to, and whether its name matches the name of the project.
The payment schedule and how much of it falls at handover. The bigger the tail, the more it matters to know in advance where that money comes from if selling before completion does not work out.
The assignment threshold in the contract — the share of the price at which the developer permits an exit. On a project with this horizon that clause is central.
And the phasing: which phase your property sits in and what is scheduled to be built around it in the same years.
Written breakdowns of subjects the English channel has not filmed.
Twice the area of Palm Jumeirah, dredged in the mid-2000s, abandoned for fifteen years and relaunched in 2023. What belongs at the top of the model rather than in a footnote.
−3% 2 BR · Apartment
AED 4 500 000 AED 4 650 000
These are official DLD readings for the entire emirate; a district split, Palm Jebel Ali included, is not made public. Use them as context for the prices on this page — registered sales for the building you pick I pull on request. Source: Dubai Land Department, read 15/08/2026.
The quarterly Land Department index is one number for the whole emirate. The monthly one counts villas and apartments separately — and in 2026 that is the point, because a blended average masks how far the segments have diverged.
The month split by completion status: 72.8% of deals were off-plan, 27.2% ready homes. Ready-home volume rose 11.4% on the month, while off-plan was the only segment down both on the month and on the year (−45.3%). The practical read: there is room to negotiate on apartments and on off-plan, far less on finished villas in established communities. Index base is January 2021 = 100 — a villa reading of 292.5 means growth of 192.5% from that mark, not a premium over a 2021 peak. Monthly ValuStrat market review for July 2026, checked 24/08/2026.
Knight Frank counted 500 Dubai home sales above US$10m in 2025, worth US$9.05bn, against 30 in 2020. The first half of 2026 added 296 more worth US$5.1bn, a half-year record. Where the money went and why the top of the market held up.
In March 2024 Nakheel and Meydan were folded into Dubai Holding and their boards dissolved. By 2026 Palm Jebel Ali has 544 villas on Fronds A–F and 728 on K–P in finishing works, and 892 homes at Jebel Ali Village are being handed over. What changed for buyers, and what did not.
Nakheel has released 44 beachfront villas on Palm Jebel Ali’s Frond F: Beach Collection (5–6 beds, 7 500–8 500 sq ft) and Coral Collection (6–7 beds, up to 12 500 sq ft), ten designs by NAGA, SAOTA, LW Design and LOCI. 544 villas are under construction; the first mall, The Yard, opens in 2027.
Nakheel awarded AED 3.5bn of contracts for 544 Palm Jebel Ali villas due in Q4 2028; Dubai Retail is building The Yard, the island's first retail hub with 26 concepts, for 2027; and Select Group became the first private developer on the island. How a stalled project is turning into a district.
The second palm island, reclaimed long ago and revived after a long pause. Relaunched projects come with their own set of questions.
Dubai’s second palm archipelago, restarted after a long pause. Its dimensions are worth stating in full, because they are what explains its effect on the market — including on the mainland behind it.
A five-bedroom villa is the most sought-after coastal format, which makes it a convenient way to compare locations. Four reference points, and the three factors behind the near-twofold gap.
Tell me which building or unit it is. Before you make an offer I will bring the registered transaction history, the current service charge and the real letting prices of comparable units.
Ask on WhatsAppTelegram is the fastest way — I answer personally.
Message on Telegram