
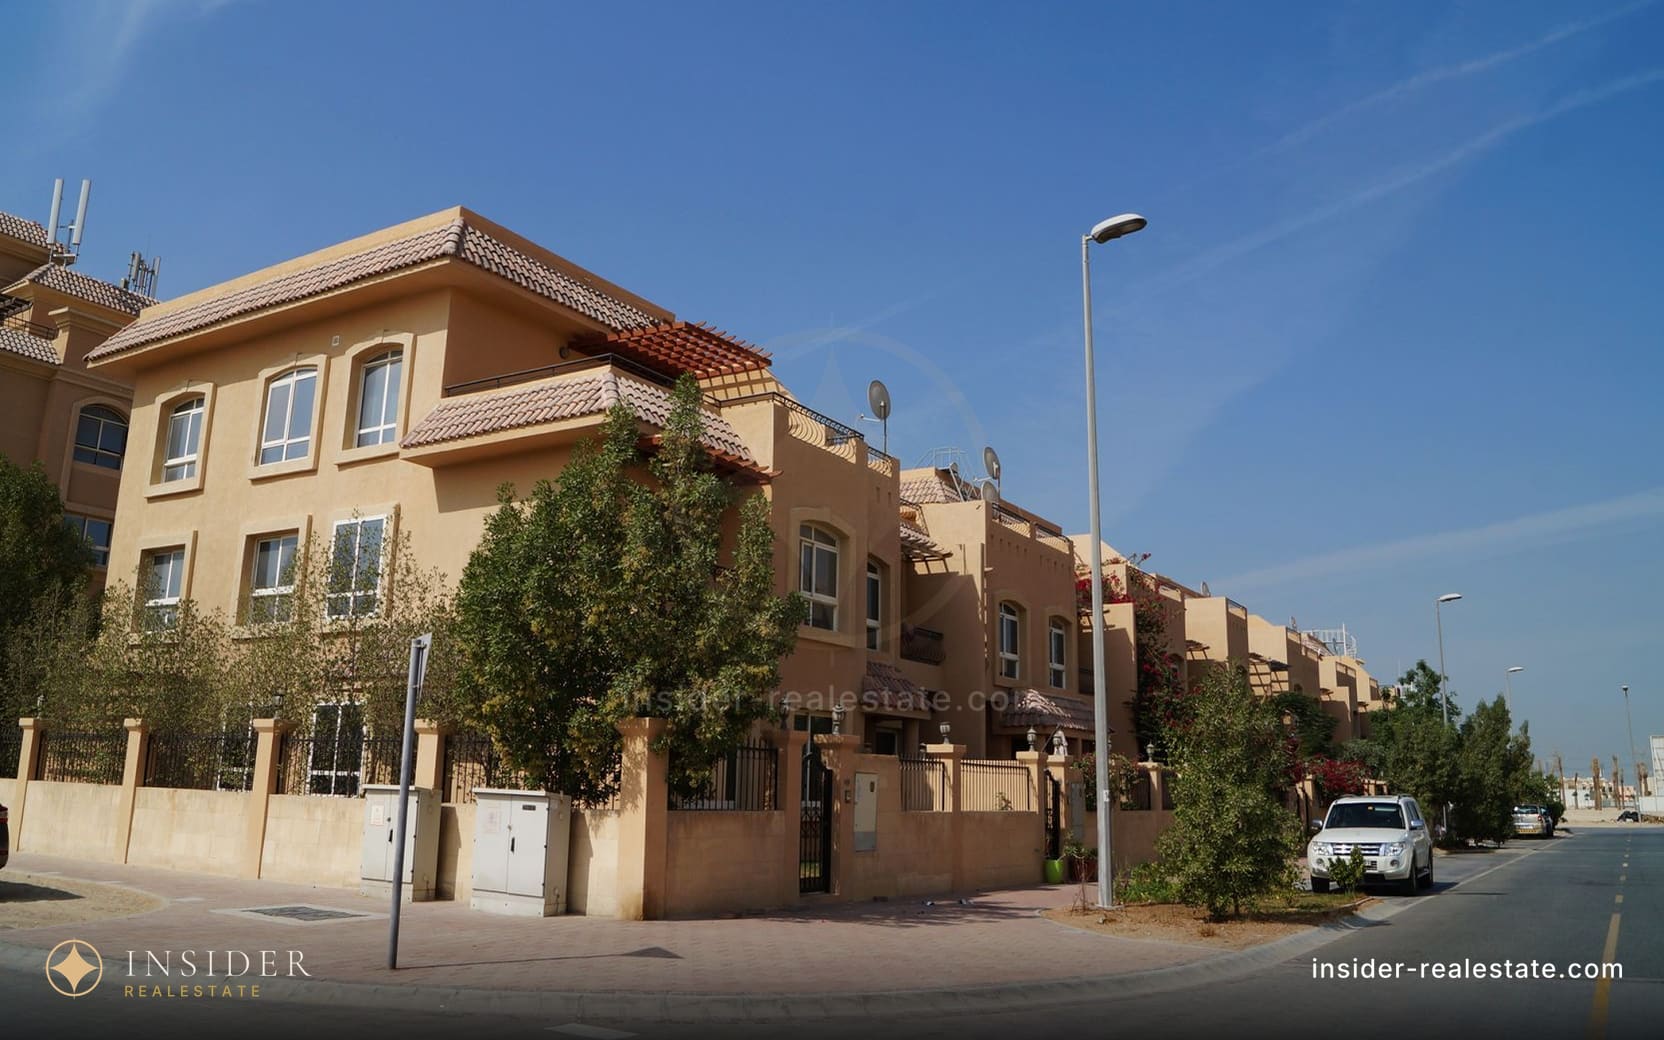
 Photo of the community
UniEstate
A mid-market developer with a portfolio spread across four districts at once — JVC, Arjan, Dubai Sports City and Dubai Silicon Oasis — best known for finishing a site that sat frozen for nearly a decade under a different name.
1 lot in stock across 1 project. Of the 1 with a known status: 1 ready, 0 under construction. By median price — 137th of 139.
- A budget entry into an established residential district
- Move-in-ready housing without off-plan risk
- An investor who cares more about price per square foot than address
- Not for buyers wanting a premium-brand story
Median price $170K AED 625 000
Entry price $170K AED 625 000 — the cheapest lot
Completed stock 100% no discounted lots right now
Where they build
The districts where this developer has the most lots in our stock.
JVC 1
The company in brief
Checkable facts about the developer itself. Unlike the figures above, these are not about our stock and do not move with what happens to be listed today.
- Portfolio
- projects in JVC, Arjan, Dubai Sports City and Dubai Silicon Oasis
- Prime Tower, JVC
- delivered in 2020; the site was originally launched by a different developer in 2008 and sat undeveloped for nearly a decade
- Segment
- mass-market housing in the mid price range — studios and one- to two-bedroom units
What kind of developer this is
Who this is, and what stands out about its reputation
UniEstate is a mass-market developer with a portfolio spread across several of Dubai's residential districts at once, with no tie to one neighbourhood or one design concept. That makes it more of a generalist mid-market player than a niche developer with a recognisable style: the product resembles what dozens of neighbouring companies build in the same districts, and the competitive edge is price and the plain fact of getting a building delivered.
A notable share of the company's reputation traces to one specific story: a JVC tower it eventually delivered was originally launched for sale by a different developer back at the peak of the construction boom and sat as a frozen construction site for years — an ordinary fate for dozens of Dubai projects from that crisis period. UniEstate took over the site, relaunched it under its own name and carried it through to handover. On a market where abandoned pits are not rare, the ability to finish someone else's frozen project is itself a meaningful fact about a company.
What it actually builds
The company's portfolio is primarily compact mass-market apartments — studios and one- to two-bedroom units, with no claim to premium positioning or distinctive architecture. The geography is spread across several districts at once, from JVC to Arjan, Dubai Sports City and Dubai Silicon Oasis, which points to a strategy of entering wherever there is available land and mid-market demand, rather than building out one recognisable neighbourhood.
This kind of product targets a buyer for whom entry price and move-in readiness matter more than address or brand. Layouts here are functional rather than experimental, and finishing sits at the level the mass market expects, without the premium materials or design choices that would justify a meaningful markup.
The site-history risk — worth checking separately from the brand
Reviving a frozen project is an achievement, but also a source of legal questions that are not always obvious to a new buyer. When a site changes developer mid-cycle, what matters is exactly how that change was structured: whether the plot and licence were bought out in full, whether claims from the first wave of buyers were settled, whether the new project is registered in the regulator's current record under the new name and a new escrow account.
For a buyer this means due diligence on that specific property cannot stop at checking the current developer — it is worth pulling the site's history from before the change of ownership too. That is not a reason to walk away from the deal, but a reason not to assume "the building is delivered, so it must be clean," and to ask a lawyer for the full registration chain for that specific plot.
How it lives after handover
In the mass-market segment where the company operates, the main factor in quality of life after move-in is not architectural detail but discipline around the service charge and the management company: whether it is fully collected, whether it is spent on genuine upkeep rather than deferred. In residential districts like JVC and Arjan this shows especially clearly, because dozens of comparable buildings sit nearby and competition for tenants runs partly on the state of common areas.
A separate practical point: the portfolio's scattered geography means the operating experience of one of the company's buildings does not necessarily transfer to another — a building in JVC and one in Dubai Silicon Oasis are most likely managed by different companies with different results, and that is worth checking for each specific address rather than relying on the developer's name as a whole.
What to check before buying
For any of the company's projects — current registration status in the developer register and an escrow account for that specific building. For properties with a change-of-developer backstory — separately, the legal cleanliness of the site handover and the absence of unresolved claims from earlier buyers.
The real condition of the company's already-delivered buildings in the same district — how lifts, facade and landscaping look several years after move-in, not in launch-day photos. Payment plan terms on the current under-construction property and what happens to them if a payment is late.
How I work with its properties
With this developer I always start by asking whether the specific property has a change-of-site-ownership backstory — that changes the scope of checking before a straightforward deal. If it does, I pull the plot's full registration history, not just the current developer's, and show the client exactly what has been settled and what has not.
Otherwise I treat the company's projects as mass-market with a reasonable entry point: I compare price per square foot against neighbouring buildings in the same district, check the real condition of already-delivered properties, and do not let "premium" marketing outweigh the fact that the product is functional rather than one-off.
Projects by UniEstate
All projects →UniEstate listings in stock
All stock → Photo of the community What these numbers mean, and what they do not
The developer is inferred from the project name — there is no developer column in the base. So the figures describe our stock, not the company's share of the Dubai market: a developer sitting on an enormous volume of completed housing can look smaller here than one whose projects reach the resale market more often.
These are asking prices, not closed transactions. For a specific building I pull the registered Land Department sales and show where deals actually closed.
Other developers
All developers → Questions
UniEstate: questions and answers
How much does a UniEstate apartment cost?
The median across this developer's lots in our stock is $170K (AED 625 000), with entry from $170K. The figures come from asking prices in our base, not from the UniEstate price list, and they are recalculated nightly to reflect what is actually for sale today.
Is UniEstate a reliable developer?
Delivered: projects in JVC, Arjan, Dubai Sports City and Dubai Silicon Oasis. Check UniEstate in the Land Department’s open register, not in the marketing: licence status, per-project construction progress and the registered escrow account are all there. Off-plan payments land in that escrow under RERA supervision and reach the developer only against verified construction milestones. The full dossier is further up the page.
What projects is UniEstate building?
Above on this page: 1 project by UniEstate from our catalogue, each with a passport covering floors, units, handover and bedrooms. The districts holding most of its lots are grouped under “Where they build”. Lots on sale, when there are any, sit right under the project.
Should I buy from UniEstate direct or through a broker?
For an off-plan buyer the price is identical, because the developer covers the broker’s commission. Going straight to UniEstate is therefore no cheaper, and the choice there is limited to its own projects — you will not get a comparison with neighbouring buildings or a candid read on handover dates. On resale and assignment the commission is standard: 2% plus VAT.
Is UniEstate worth buying
It depends what you are buying and why. Send me your budget and the job it has to do — I will tell you which of this developer's projects make sense right now and which I would walk past.
Ask on WhatsAppAsk a question
Telegram is the fastest way — I answer personally.
Message on Telegram