
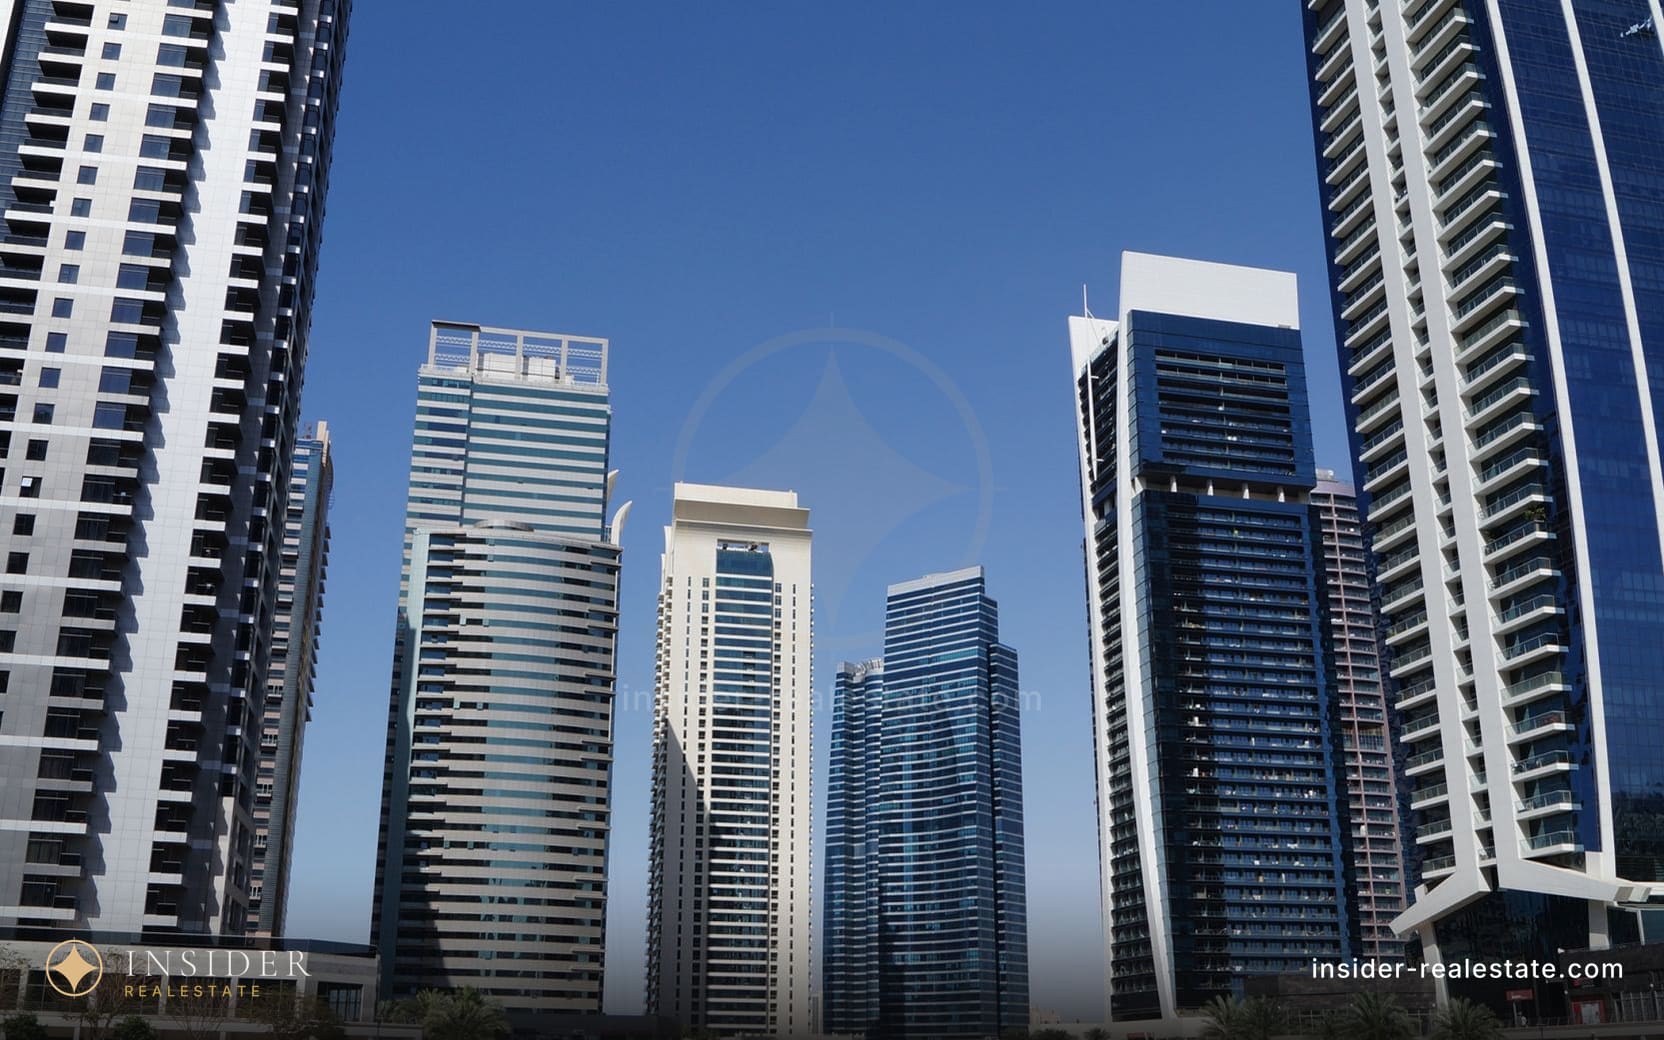
 Photo of the community
Bonyan International Investment Group Holding
An investment group with offices from Dubai to the Caribbean, for which real estate is one line of a diversified business rather than the only one — visible in how scattered its portfolio is across emirates and countries.
1 lot in stock across 1 project. By median price — 85th of 139.
- A buyer who values a developer's financial diversification
- Ready-to-move JLT housing with years of operating history
- Not for buyers seeking a narrowly focused residential developer
- Not for anyone counting on one recognisable architectural signature across the company
Median price $449K AED 1 650 000
Entry price $449K AED 1 650 000 — the cheapest lot
Per square foot $391 AED 1 435 / sq.ft, median
Where they build
The districts where this developer has the most lots in our stock.
JLT 1
The company in brief
Checkable facts about the developer itself. Unlike the figures above, these are not about our stock and do not move with what happens to be listed today.
- Entered real estate
- 2002
- Registered as a Dubai developer
- December 2007, registration number 257 with the Land Department
- Office geography
- all UAE emirates, plus Jordan, Qatar, Oman, the British Virgin Islands, the Bahamas, the Cayman Islands and other jurisdictions
- Dubai Gate 2, JLT
- delivered 2017–2018 — 35–36 storeys, around 440 units
What kind of developer this is
Who this is — an investment group, not a housing developer in the narrow sense
Bonyan International Investment Group Holding entered real estate not as a specialist residential developer but as part of a broader investment business spanning planning, project management, construction and property management across the full cycle — from development to subsequent leasing and upkeep. Formal registration as a Dubai developer followed a few years later, giving the company a Land Department register number and more than two decades of presence in the local market.
That origin sets it apart from developers for whom housing is the sole business: here, real estate sits within a much wider investment structure with offices across several countries and continents, meaning decisions on specific projects are made in the context of the group's broader asset portfolio rather than in isolation.
Scattered geography — a signal of a model, not chaos
The company is present not only across all UAE emirates but also in Jordan, Qatar, Oman, and several offshore jurisdictions typical of international holding structures. That geography is unusual for Dubai's residential property market, where most developers are local companies focused on one city, or at most a couple of emirates.
For a buyer, this means you are not dealing with a narrowly focused construction firm but with part of a much larger, legally layered structure. That is not inherently bad — scale and diversification usually mean resilience to swings in any single local market — but it calls for more care over exactly which entity within that structure genuinely holds the obligations for a specific building.
What has been built in Dubai — a mixed-use JLT portfolio
In Dubai the company has delivered residential, commercial and hospitality projects, including in the Jumeirah Lake Towers cluster, where it has two separate towers under the shared Dubai Gate name. That mixed-use approach — housing, offices and hospitality at once — matches the group's broader investment nature rather than a narrowly residential one.
By the time these towers were delivered, JLT was already an established business and residential cluster with developed infrastructure — a metro station, the lakeside promenade, retail on the ground floors — reducing the risk typical of emerging corridors for a buyer: the district does not need to be waited for, it already works.
How it lives after handover — what a long JLT history means
The company's JLT buildings were delivered long enough ago to have their own operating history of several years, meaning facade condition, lift performance and management quality can be judged in practice, not on promises. For a tower of this age that matters especially: salt air and heavy use test mechanical systems harder than in the first years after handover.
The group's diversified structure in theory means steadier funding for the management company — less risk that the service charge is the sole source of funds for upkeep. But that is worth checking directly on the specific building, rather than taking on faith because of the parent group's scale.
What to check before buying
Exactly which legal entity within the Bonyan structure is party to your contract and developer of the specific building — with a branched holding structure this is not always obvious from the project name. The specific tower's actual condition years after handover — facade, lifts, management company performance, service-charge history.
If considering a new or still under-construction company project — the escrow account status and registration in the current developer register, regardless of the long-standing registration number. The registered resale transaction history for the specific building of interest — how liquid it is on the JLT secondary market.
How I work with its properties
With this developer I always clarify for the client that behind the Bonyan name stands a diversified investment group, not a narrowly focused residential developer — and explain how that shifts the risk balance: financial resilience is above the market average, but architectural signature is less uniform than among developers focused solely on housing.
For already-delivered JLT buildings I check the actual operating history — especially useful here, because the buildings are old enough to give an honest answer on upkeep quality. For new projects I separately verify the specific developer entity within the group, and do not treat the company's general name as sufficient reassurance on its own.
Projects by Bonyan International Investment Group Holding
All projects →Bonyan International Investment Group Holding listings in stock
All stock → Photo of the community What these numbers mean, and what they do not
The developer is inferred from the project name — there is no developer column in the base. So the figures describe our stock, not the company's share of the Dubai market: a developer sitting on an enormous volume of completed housing can look smaller here than one whose projects reach the resale market more often.
These are asking prices, not closed transactions. For a specific building I pull the registered Land Department sales and show where deals actually closed.
In the news
Bonyan International Investment Group Holding: how to read a title deed
A developer with a JLT tower completed in 2018. The title deed is the only document that proves what you own, and most buyers glance at it once — here is what each line means.
Other developers
All developers → Questions
Bonyan International Investment Group Holding: questions and answers
How much does a Bonyan International Investment Group Holding apartment cost?
The median across this developer's lots in our stock is $449K (AED 1 650 000), with entry from $449K. The median per square foot is $391. These are asking prices out of our own base, recalculated every night; they follow what the developer and its sellers actually have on the market, not the price list on a corporate site.
What projects is Bonyan International Investment Group Holding building?
Our catalogue holds 1 project by this developer, each with a building passport: storeys, unit count, handover date, the mix of bedrooms. The list is on this page, and the districts where the developer has the most lots in stock are in the “Where they build” block. Under each project sit the lots on sale, where there are any.
Should I buy from Bonyan International Investment Group Holding direct or through a broker?
For an off-plan buyer the price is identical, because the developer covers the broker’s commission. Going straight to Bonyan International Investment Group Holding is therefore no cheaper, and the choice there is limited to its own projects — you will not get a comparison with neighbouring buildings or a candid read on handover dates. On resale and assignment the commission is standard: 2% plus VAT.
Is Bonyan International Investment Group Holding worth buying
It depends what you are buying and why. Send me your budget and the job it has to do — I will tell you which of this developer's projects make sense right now and which I would walk past.
Ask on WhatsAppAsk a question
Telegram is the fastest way — I answer personally.
Message on Telegram