 −14%
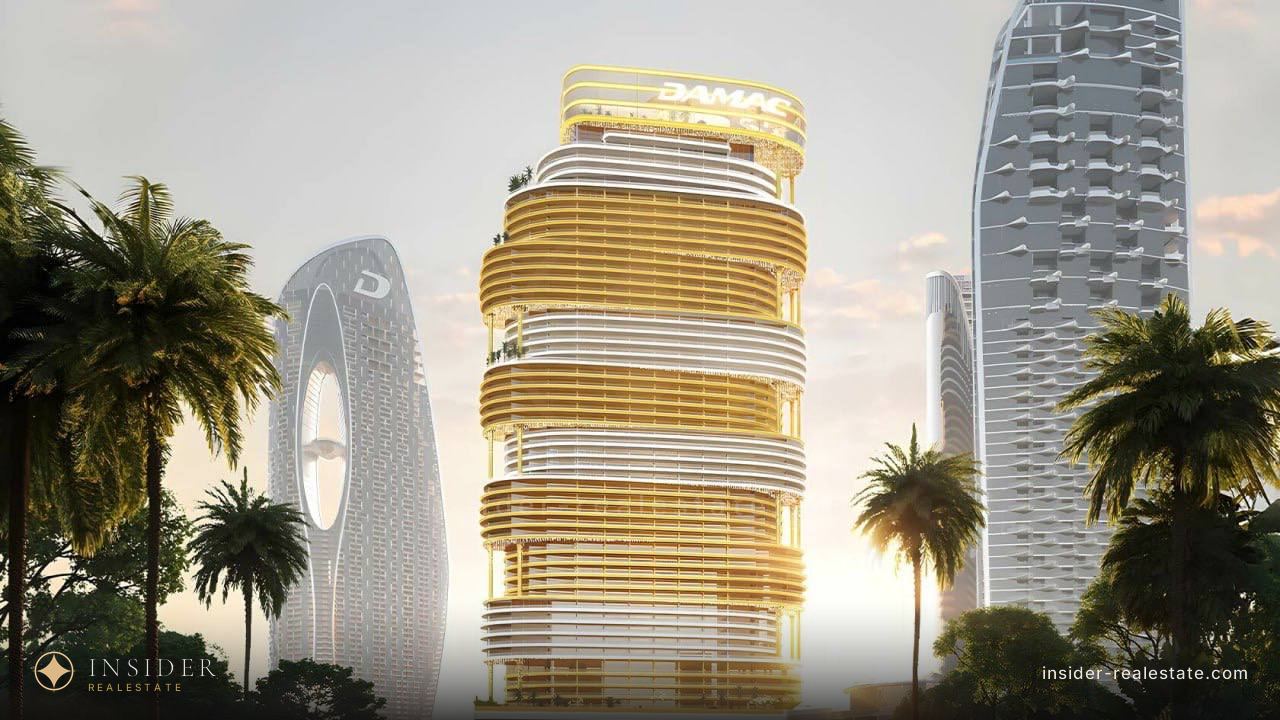
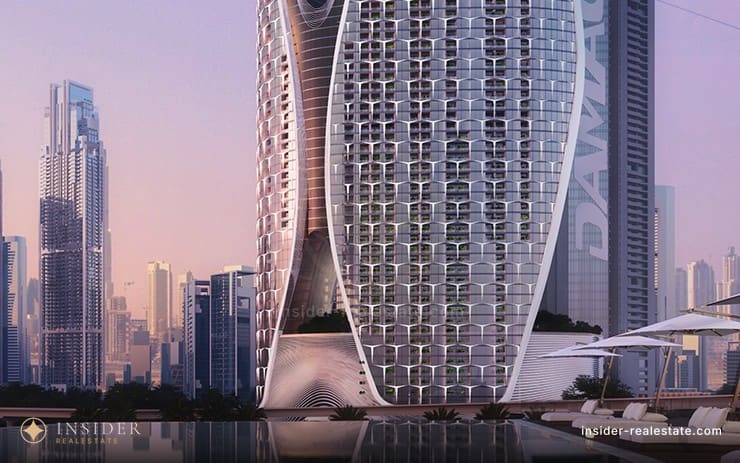
Safa Two by de GRISOGONO - (aykon city 3)
1 BR · Apartment
AED 1 550 000 AED 1 809 000
A villa district wrapped around Safa Park, with a short line of very tall towers along its Al Wasl Road edge — two entirely different products at one address.
4 units in stock. 4 with a confirmed status: 0 ready, 4 under construction. 46th most expensive of 88 districts by median price.
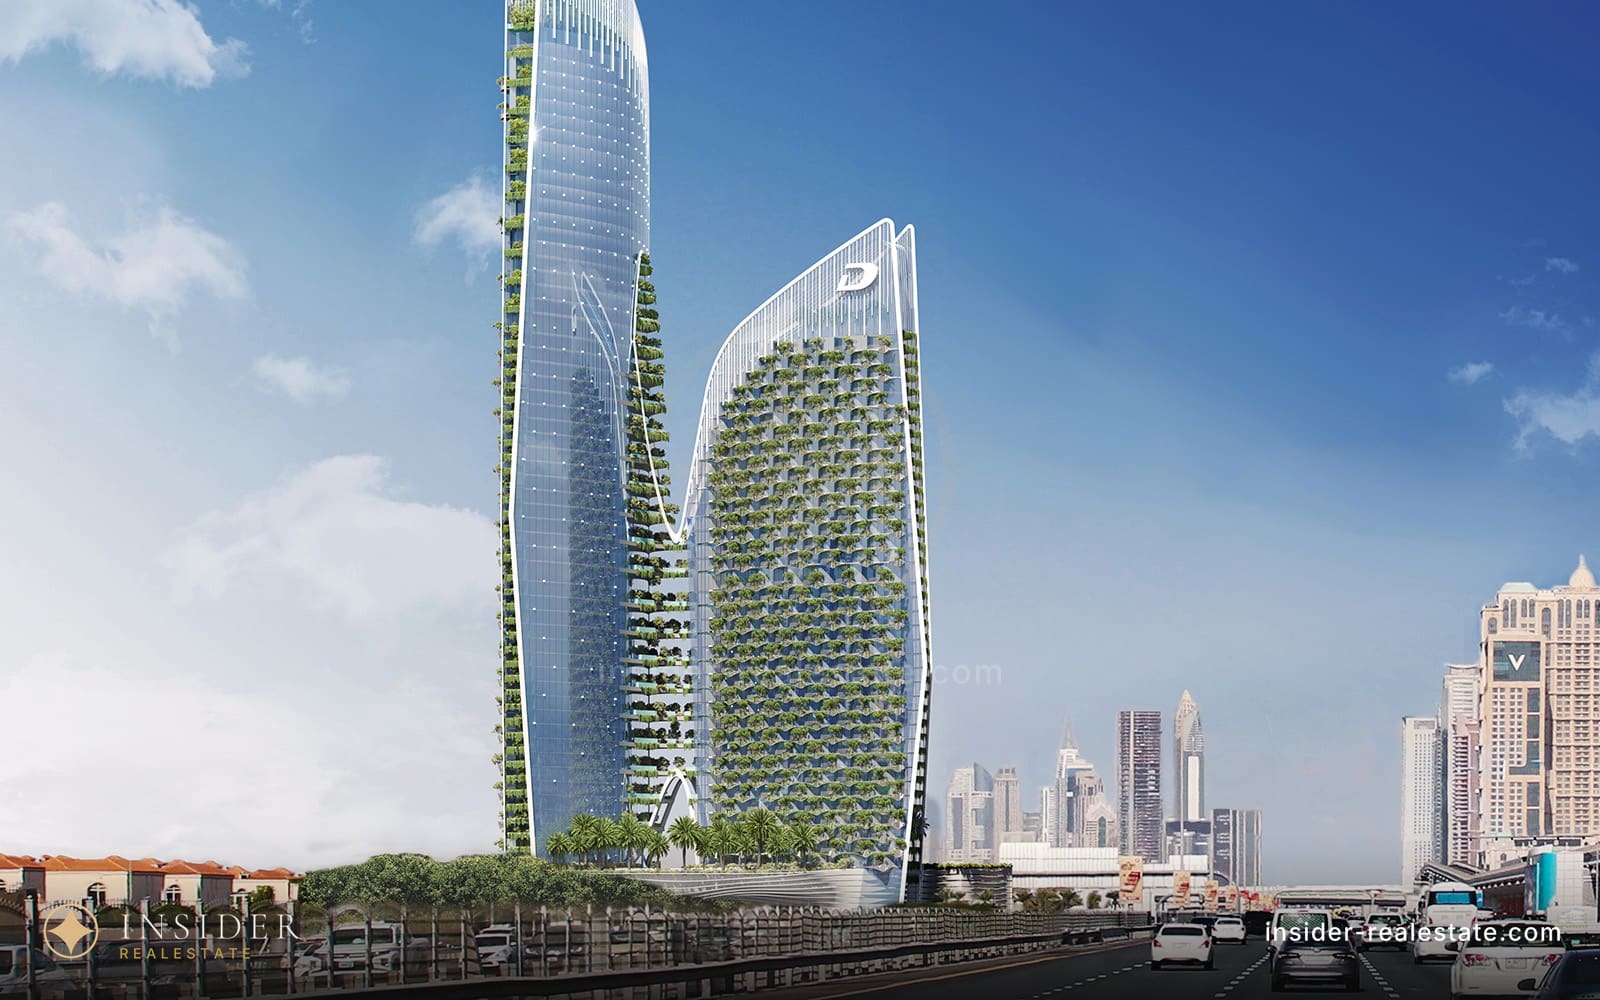
Al Safa is the stretch of ground between Al Wasl Road and Sheikh Zayed Road, west of Business Bay and east of Jumeirah, wrapped around Safa Park. It is one of the oldest established residential areas in central Dubai and it looks the part: wide streets, mature trees, single-storey and two-storey villas on generous plots.
Safa Park itself is the organising fact. It is one of the city’s oldest large public parks, and in 2016 the Dubai Water Canal was cut along its southern edge, which took a strip of the park and gave the district a waterfront it did not previously have.
Almost all of the built area is Al Safa 1 and Al Safa 2 — villa sub-communities, largely occupied by families on long leases. The towers are the exception rather than the rule: a short line of them stands on the Al Wasl Road frontage facing the park, and everything behind them stays low.
That is the whole character of the place. It is central without being vertical, which in this part of Dubai is close to unique.
The villas and the towers here are not variations on a theme; they are different assets with different buyers and different ownership rules, and confusing them is the most common mistake made about this district.
The villa stock is mature, low-density and mostly rented rather than traded. Plot sizes are large by current standards and the housing itself is old, which means a buyer is buying land and location rather than a finished product.
The tower stock is new, off-plan and concentrated: a handful of very tall residential buildings on the park edge, delivered by a single developer. That is where essentially all of the freehold apartment supply in Al Safa comes from.
When a listing says “Al Safa”, establish which of the two it belongs to before reading anything else about it.
Central Dubai is a patchwork of freehold and non-freehold land, and Al Safa sits in the part of the city where that patchwork is at its most uneven. Much of the villa land here is not available to foreign buyers in freehold.
The towers on the Al Wasl Road frontage are the freehold route into the district for an overseas buyer, which is why the off-plan stock dominates the listings even though it is a small fraction of the built area.
Confirm the designation for the specific plot or building rather than for the district name. This is not a formality here — it decides whether the purchase is possible at all.
Downtown, DIFC and Business Bay are all a few minutes away, and Sheikh Zayed Road runs along the district’s eastern edge with the Red Line metro on it. The beach at Jumeirah is a short drive down Al Wasl Road, and City Walk is immediately to the north.
What distinguishes this from other central addresses is the ground itself. A tower in Business Bay looks at other towers; a tower on the Al Safa frontage looks over a park and a district of villas that is not going to be built out vertically.
That is a durable advantage rather than a temporary one, because the constraint is the existing villa fabric, not a planning promise.
The cost of the same centrality is the traffic. Al Wasl Road and the Sheikh Zayed Road interchanges are busy at both peaks, and no amount of park frontage changes that.
Orientation, floor by floor. The towers stand close together on a narrow frontage, and the difference between a park-and-canal outlook, a Burj Khalifa outlook and the side of the neighbouring building is decided by the unit, not by the building.
Read the floor plate rather than the render. Marketing images for this frontage are drawn from the best available position in the stack, and the stack is tall.
Delivery risk, because nearly all of the freehold stock here is one developer’s off-plan product. That concentrates the exposure in a way that a district with several developers does not.
And resale depth before handover, which in a district this small and this new is thinner than the location alone would suggest.
A buyer who wants a central address with an outlook that will not be built out, and who is comfortable with off-plan delivery risk to get it.
An end user who values the park and the low-rise surroundings more than the amenity density of a masterplanned district.
It suits poorly anyone who needs stock to choose from: the freehold supply here is a handful of buildings, and if none of them fits, the district has no second option.
It also suits poorly anyone who wants a villa in this specific district without first checking whether they are permitted to own one.
Al Wasl and City Walk immediately north — the same corridor, more finished, denser, and with a wider choice of buildings.
Business Bay across Sheikh Zayed Road — comparable centrality, far deeper supply, and none of the low-rise outlook.
Jumeirah and Umm Suqeim for villa living closer to the beach, where the freehold picture is also uneven and worth checking building by building.
Each of those is covered with current stock composition and median prices in the areas section.
Written breakdowns of subjects the English channel has not filmed.
Mature low-rise wrapped around Safa Park, with a short line of very tall buildings on the Al Wasl Road frontage. Two products at one address — and several towers with "Safa" in the name that are registered somewhere else.
−14% 1 BR · Apartment
AED 1 550 000 AED 1 809 000
−13% −13% 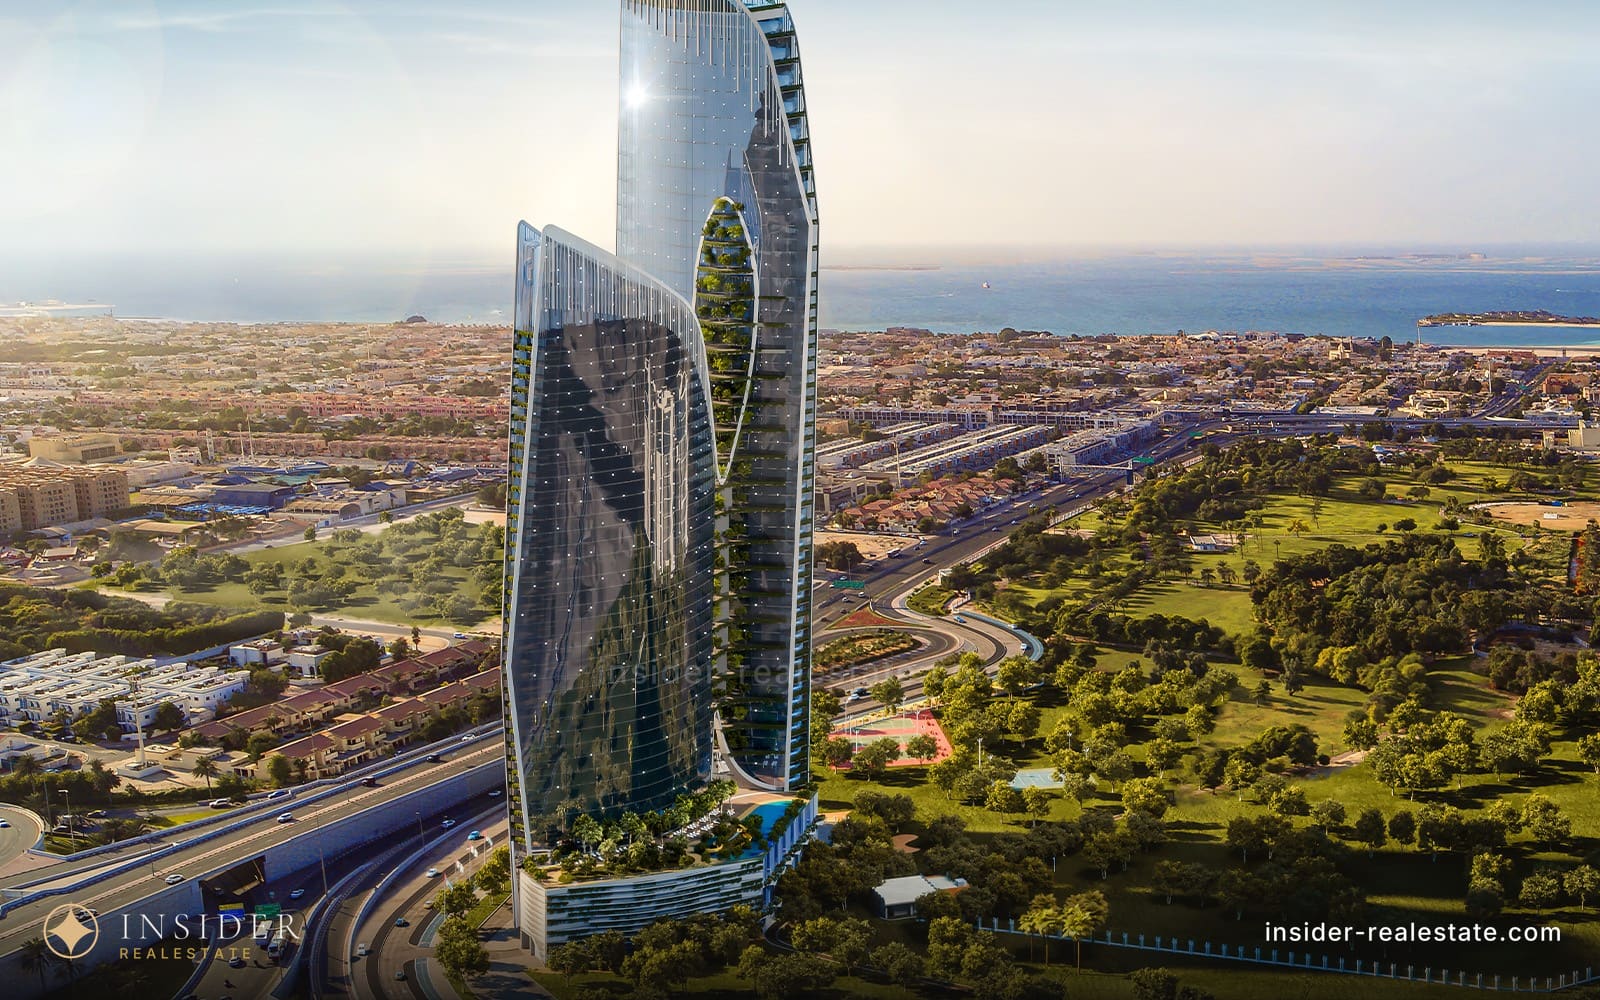 −10%
The index covers the emirate as a whole; the Land Department publishes no separate figure for Al Safa. Read it as backdrop — is the market rising or flat — against the prices above. Deals in a particular Al Safa building I can pull separately if you ask. Source: Dubai Land Department, read 15/08/2026.
The DLD index above comes out quarterly and does not separate segments. The monthly price index treats villas and apartments apart, which in 2026 is essential: a market-wide average conceals that the two have gone different ways.
Off-plan took 72.8% of the month's deals and ready homes 27.2%. Ready volume was up 11.4% on the month, and off-plan alone fell both month on month and year on year (−45.3%). So negotiation is realistic on apartments and off-plan, much less so on completed villas in established communities. Index base is January 2021 = 100 — a villa reading of 292.5 means growth of 192.5% from that mark, not a premium over a 2021 peak. Monthly ValuStrat market review for July 2026, checked 24/08/2026.
Lyra is a roughly 20-storey tower of 349 apartments in Majid Al Futtaim’s forest community, Ghaf Woods. Registered with the Dubai Land Department on 26 October 2026, it starts at about AED 1.19m for a one-bedroom on a 50/50 plan.
In October 2024 UK-founded LEOS moved its global headquarters to Dubai and announced a $7bn fund for 10+ UAE projects. A year later it launched LEOS Royal with Dubai Holding: about 800 villas and townhouses in Wadi Al Safa 5, valued at AED 5bn+. How to read a developer like this.
A listing may name a sector, a community or a project — three different levels. Confusing them costs buyers real money.
The district name in a listing can mean almost anything. The plot number is the only unambiguous identifier of a property.
Name the Al Safa building or unit you are looking at, and I will pull its registered sales history, today's service charge and the rents comparable units actually achieve — before you offer, not after.
Ask on WhatsAppTelegram is the fastest way — I answer personally.
Message on Telegram